How much down payment to build a custom home in Washington? Anasazi Builders uses about 20% of the total project cost as a starting point when discussing construction loans. Some mortgages for a finished spec home allow as little as 3% down. Your lender determines what you qualify for and how much cash you’ll need.
The short version
- About 20% is a planning figure for construction financing. Requirements vary by lender and loan program.
- A finished spec home may qualify for a purchase mortgage with 3% down.
- If you already own the lot, ask how the lender will treat any equity or remaining land loan balance.
How much should you plan to put down on a construction loan?
Start by asking your lender what the down payment is based on and what portion must be paid in cash. The approved financing amount helps set the scope of the build. Anasazi explains the next steps in its guide to construction loan basics.
If you’re exploring a build in the Tri-Cities, see custom home design in Pasco, WA. Once you know what the lender has approved, you can plan your custom home project around that budget.
How does owning land affect your down payment?
If you still owe money on your lot, ask whether the construction loan can pay off that balance as part of closing. John Worlund describes how that works on projects financed this way: “The first item that comes out of the construction loan is to pay off the land.” Whether the balance can be rolled into the loan and whether equity counts toward your contribution depend on the lender and loan program.
Ask your lender how it values the lot and how much cash you would still need after it accounts for any equity or existing loan. You can see real homes to get a sense of how project scope varies before you settle on a plan.
Is the down payment lower when you buy a finished spec home?
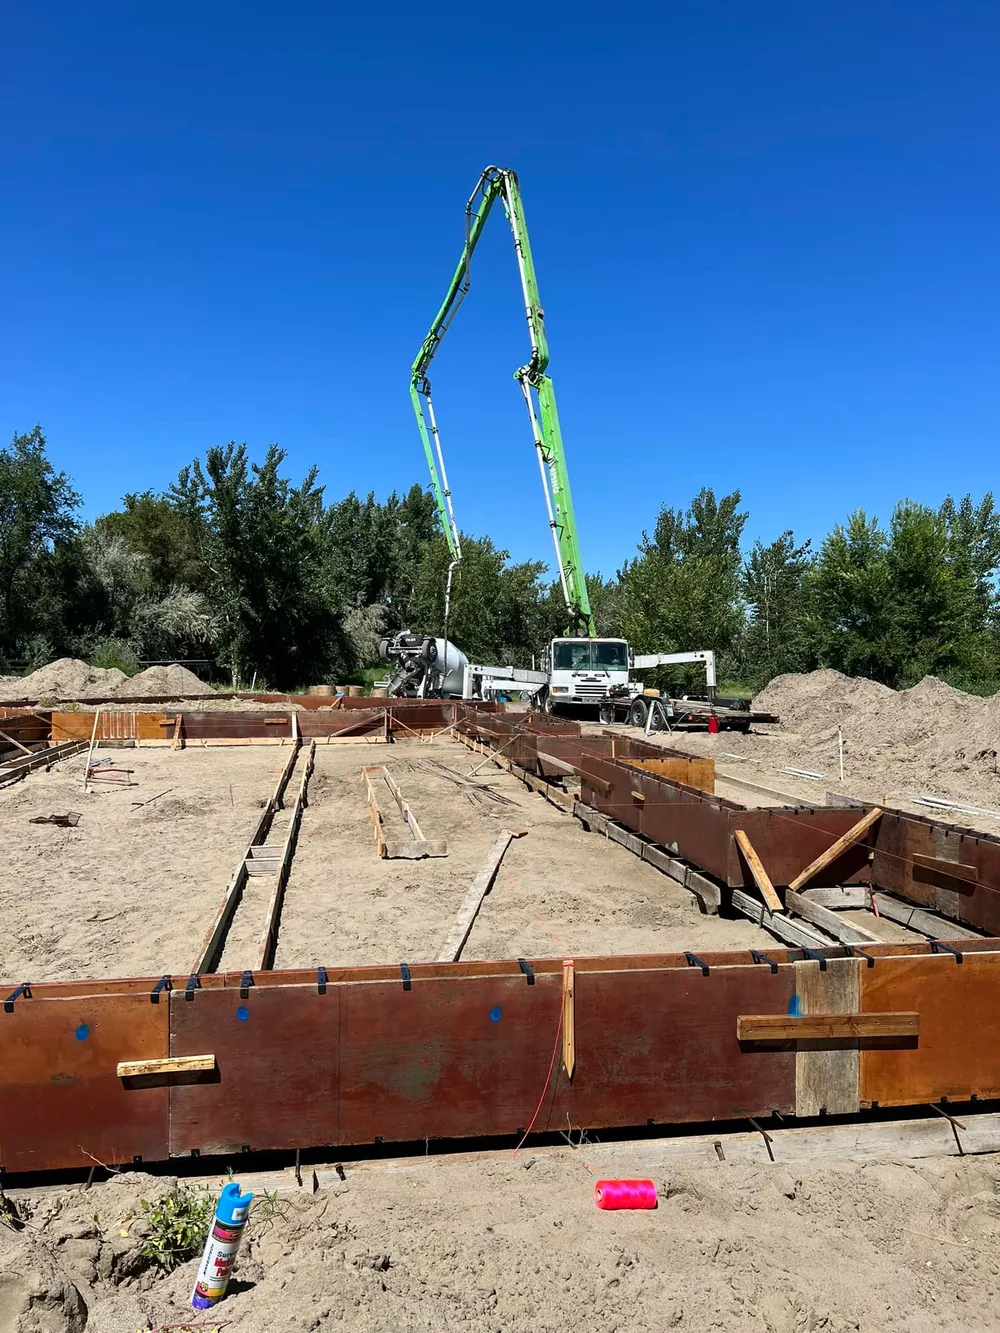
It can be. A finished spec home may qualify for a standard purchase mortgage, including some programs that allow 3% down. A custom build on your lot uses construction financing. The lender reviews the lot and building plans before setting the required contribution. See Anasazi’s comparison of building on your land and buying from a builder for more on these two paths.
| Decision | Custom build on your land | Finished spec home |
|---|---|---|
| Down payment | About 20% as a planning figure | As little as 3% on some eligible mortgages |
| Buyer involvement | You make design and finish decisions | You buy a home the builder has already finished |
| Changes | Decisions can be planned into the build | Changes to the finished home are handled separately |
Frequently Asked Questions
Is 20% down a hard rule for a construction loan?
Requirements vary by lender and loan program. Treat 20% as a starting point and ask your lender what contribution it requires for your project.
If I own my lot outright, can the equity count toward my down payment?
It may. Ask the construction lender how it values your lot and whether it will credit the equity toward your required contribution.
Does the 3% figure apply to buying a finished spec home?
Some purchase mortgages allow a qualified buyer to put 3% down on a finished home. Ask your lender whether the mortgage you qualify for offers that option.
If you want to compare your lender’s approved amount with your lot and plans, talk through your budget with John.